Two matching new villas on one block
A Property Investment Store Strategy
📷
images/dual-villa-hero.png
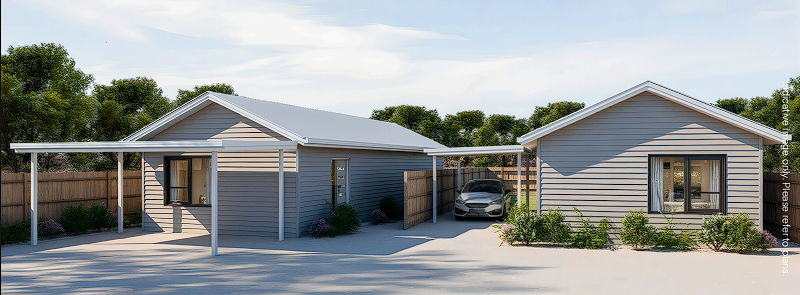
Two matching new villas side by side on one block, the actual product

One block of land.
Two brand-new homes.
Built to work twice as hard.

Too much tax. A mortgage that won't die. Not enough super. Kids priced out of the market. The dual villa strategy tackles all four at once: two self-contained villas on one parcel of land, split onto two separate titles, so you get two rents and two depreciation schedules from a single purchase.

Free. 15 minutes. No obligation. We'll tell you honestly if a dual villa suits your numbers.

1
Land Purchase
2
Brand-New Villas
2
Separate Titles
2
Rental Incomes

How one strategy speaks to all 4 problems

  • 💸
    Too much taxTwo brand-new dwellings mean two depreciation schedules, while stamp duty is still calculated on one land component.
  • 🏠
    A mortgage you'll never clearTwo separately titled villas mean two incomes and two growth engines, and the choice to sell one to smash your home loan while the other keeps working.
  • 🌅
    Not enough for retirementKeep one villa long-term as an ongoing income asset working alongside your super.
  • 👨‍👩‍👧
    Helping your kids get aheadOnce your own numbers are sorted, the second villa is a natural head start for the next generation.
The real problem

One asset, working alone, is a slow way to fix four problems.

You're already carrying too much tax, a mortgage that barely moves, and a super balance that isn't tracking toward the retirement you pictured. A single investment property helps, but it only pulls one lever at a time: one income, one depreciation schedule, one growth line.

Meanwhile the clock keeps running. Every year without a second lever is another year of paying full tax, carrying the full mortgage, and pushing back the point where you can genuinely help your kids.

You've already done the hard part. You own your home, you've built some equity, and you're ready to act. What's been missing isn't effort, it's a strategy built to move on more than one front at once.

The external problem

Too much tax. A mortgage that barely moves. Super that isn't tracking toward the retirement you want.

"I'm doing everything right. So why does it still feel slow?"

The internal problem

It's frustrating to know a better structure exists, tax-effective, cash-flow positive, growth-focused, and not be using it yet.

"There has to be a faster way to do this."

The philosophical problem

You've worked hard and made the sensible moves. You're entitled to a strategy that does more than one thing at a time.

"Why should this take twice as long as it needs to?"

Where this discipline comes from

We didn't invent this approach for villas. We learned it building SDA.

Property Investment Store has been in the Specialist Disability Accommodation space since the NDIS began, and we've now built more than 100 SDA homes for NDIS participants.

SDA teaches you a hard lesson fast: it was never about what the investor wanted. It was about what the participant needed, their support level, their location, their access to family, transport and services. Get any of that wrong and you don't just have a disappointing investment, you have a home that doesn't actually work for the person who has to live in it.

We've taken that same discipline and applied it to the dual villa strategy. It isn't built around what looks good on a brochure. It's built around what a suburb actually needs.

In practice, that means affordable homes, built where the existing housing stock is ageing and vacancy is already tight. Right now that means Tasmania first: it also means designing the exit before the first sod is turned. Every dual villa is built to appeal to the buyers who'll actually want it when it's time to sell: first home buyers and young couples stepping onto the ladder, and downsizers stepping off theirs into something low-maintenance and close to services. That's who we're selling to when we sell, and it's the buyer pool we build for from day one.

100+
SDA homes built for NDIS participants
Day One
Building SDA housing since the NDIS began
Need, not want
The same site-selection discipline, now applied to every dual villa
FHBs · Couples · Downsizers
The exit strategy, designed in from day one
How it actually works

Two homes. One piece of land.

A dual villa is exactly what it sounds like: two separate, self-contained dwellings built on a single block. Each villa is a two-bedroom home with its own entry, kitchen, laundry, a bathroom with a separate toilet, and a single car space. The only thing they share is the land beneath them.

That matters more than it sounds. Stamp duty on a house and land package is calculated on the land component only, and it isn't tax deductible. With a dual villa, you're paying that one land-based cost once, but ending up with two brand-new, independently rentable homes sitting on it.

We only build dual villas on land we can split. Title separation isn't a hope for later, it's a condition we screen for before a site is ever put in front of a client. Both villas are designed to be separately titled on completion, so a dual villa puts two real, individually sellable assets to work from the same purchase, structured from day one for positive cash flow so neither villa relies on your own income to service its loan.

Same land purchase, two separately titled homes.

Two separate incomes

Each villa is leased to its own tenant. If one sits vacant between tenancies, the other villa is still generating rent, so your cash flow doesn't drop to zero the way it can with a single investment property.

Two depreciation schedules

Because both dwellings are brand new, each one carries its own full depreciation schedule from the day it's built, often worth a meaningful annual tax benefit on top of the rent. Brand-new stock also tends to lease faster and hold its value better on resale than an established property.

One land purchase, two titles at completion

You're not buying two blocks of land or paying stamp duty twice. The land cost, and the non-deductible duty that comes with it, is shared across two separately titled, income-producing homes instead of carried by just one.

The plan

Three clear steps to your dual villa strategy.

The same rigorous process we use for every client, applied to a strategy built to move faster.

Step 01

A Free 15-Minute Intro Call

A quick, no-pressure conversation about your income, your equity, and your goals, so we can tell you honestly whether a dual villa, a single villa, or something else entirely is the right fit for your situation.

No pitch. No hard sell.
Step 02

Your Dual Villa Strategy Session

We model the numbers for a dual villa against your goals and timeline: combined rent, both depreciation schedules, one land cost, and what it does to your mortgage and tax position side by side.

Independent mortgage brokers are brought in early so your finance position for a dual-dwelling build is clear before anything is committed to.

Strategy before property, always
Step 03

Land Selection and Dual Build

We only present land we can split. Every site is checked for council-supported dual occupancy and clean title separation before it's assessed on growth and demand, and most don't make the cut.

From contract to handover, we manage both builds with fixed-price turn-key contracts and stage inspections across each dwelling.

We handle the complexity of two builds so you don't have to
The core strategy, doubled

How one block of land can do the work of two.

Our core strategy has always been simple: buy an investment property, let it grow, sell it, and use the profit to smash down your home loan. Repeat until it's gone.

A dual villa doesn't change that strategy, it compresses it. Instead of one dwelling generating one income and one growth line, you have two, anchored to a single land purchase.

We only build on land we can split, so both villas are separately titled on completion. That's the difference a dual villa makes to your exit: instead of one property to sell, you have two. Sell one of two and keep the other, banking a lump sum against your mortgage while a second asset keeps producing income, or sell both, or hold both. It's a genuine choice, not an all-or-nothing decision.

🏠
Villa One
Own Title
🏠
Villa Two
Own Title
One shared land purchase  ·  two separate titles on completion
1

Buy one parcel, build two villas

Land cost and stamp duty stay anchored to a single purchase while two new dwellings start earning rent.

Two tax deductions apply from day one
2

Hold both, structured for cash flow

Combined rent is designed to cover both loans so the strategy doesn't rely on your own income to run it.

Vacancy on one villa doesn't stop the other
3

Two assets grow together

Capital growth compounds across both dwellings while the land beneath continues to appreciate.

Equity builds on two fronts at once
✓

Sell one of two, or hold both

Both villas are separately titled at completion, so you can sell one as a lump sum for your PPOR and keep the other for income, sell both, or hold both for the long term.

Debt-free sooner, or a stronger retirement asset base
An illustrative example

What the numbers can look like.

Every site, build and market is different, but here's a realistic shape for a dual villa project, from one land purchase through to two separately titled, tenanted villas.

$750k
Indicative package total · $375k per villa (×2)
$150k–$200k
Indicative equity uplift, across the pair
$430–$500 / wk
Indicative rent, per villa
8–10 months
Typical build time
$15k–$20k / yr
Typical tax benefit via depreciation & gearing
2 Bed · 1 Bath + WC · 1 Car
Typical villa configuration

Illustrative example figures only, not a forecast, quote or guarantee of future performance. The equity uplift shown reflects the completed valuation of two separately titled villas against the land and build cost, not the earlier pre-construction bank valuation used to set up finance, which can occasionally land under contract price and simply calls for a finance structure adjustment. Actual land, build and rental figures vary by site, market and timing. Tax outcomes depend on your personal circumstances, always speak with your accountant.

Curious if a dual villa could work for your numbers?

Book a free 15-minute intro call. We'll model it against a single villa so you can see the difference for yourself.

Book My Free 15-Minute Call

Or call 1300 747 867

What's at stake

What happens if you stick with one property, or nothing at all?

A single investment property still works. It just works slowly. Doing nothing works even more slowly.

Every extra year spent on one income-producing asset instead of two is a year of paying more tax than you need to, carrying more mortgage than you need to, and pushing your kids' first step onto the ladder further away.

None of this is set in stone. But changing it takes a deliberate decision, and a strategy built to move on more than one front at once.

Book a free 15-minute call
  • ✕

    Still paying full taxOne depreciation schedule instead of two means leaving legitimate deductions on the table, year after year.

  • ✕

    Mortgage on the slow trackOne growth line and one rental income mean smaller lump sums and a longer road to clearing your home loan.

  • ✕

    Retirement still shortA single asset is a single engine. If it's not enough on its own, the gap doesn't close itself.

  • ✕

    Kids still locked outEvery year spent fixing your own position slowly is a year further from having the capacity to help theirs.

The other path

This was never just about property. It's about your 4 problems.

Every strategy we build exists to solve the same four things: the tax you're overpaying, the mortgage that won't move, the super that won't be enough, and the kids you'd like to help. A dual villa tackles all four from a single purchase, on the timeline a single asset would need to tackle just one.

Here's how it lines up against each one, in the order we always work through them.

Talk through your own numbers
1

Paying too much tax

Two brand-new dwellings mean two full depreciation schedules from day one, while the non-deductible stamp duty is still calculated on just one land component. More legitimate deductions, on one purchase.

2

A mortgage you'll never pay off

Two rents and two growth lines can build a bigger lump sum, sooner. Because both villas are separately titled at completion, you can sell one of two, not one of one, and put a serious dent in your home loan while the other villa keeps working.

3

Not enough for retirement

Keep the second villa rather than selling it, and it becomes an ongoing income-producing asset alongside your super, a second engine for the retirement you're actually picturing.

4

Helping your kids get ahead

Oxygen mask on first. Once your own tax, mortgage and super position is sorted, that second villa or the equity it's built is a genuine, practical way to help a child into their first property.

Why dual villas

Why a dual villa can outperform a single investment property.

Every one of these comes back to the same idea: two assets, one land purchase.

🛡️

Cash Flow Resilience

Two tenancies instead of one. If a tenant moves out of one villa, the other is still paying rent, so a single vacancy doesn't stop your cash flow entirely.

📋

Doubled Depreciation

Two brand-new dwellings carry two complete depreciation schedules. Established property, and even a single new build on the same land, simply can't match it.

🏗️

One Land Cost, Shared

Stamp duty applies to the land component once. That cost, and the cheapest part of the purchase, is carried across two income-producing homes instead of one.

🔑

Faster to Lease, Stronger to Sell

Brand-new villas typically lease faster and command stronger rent than comparable established stock, and tend to hold their value better when it's time to sell. That works for you on the way in and the way out.

🔀

Built-In Choice

We only build on land we can split, so both villas are separately titled on completion. That's a real choice at exit: sell one and keep one, sell both, or hold both, instead of an all-or-nothing decision.

🧭

Same Rigour, Two Builds

We reject the large majority of developments that cross our desk. A dual villa site is assessed against the same growth, demand and build-quality criteria as every other project we put forward.

Is this right for you?

A dual villa isn't the right tool for everyone.

Here's how to know if it's the right fit for your situation, before you book a call.

Good fit

A dual villa is probably worth exploring if

✓

You already like the idea of an investment property, but want stronger cash flow than one dwelling typically provides

✓

You want to fast-track paying off your own mortgage rather than wait out a longer strategy

✓

You want two rents and two depreciation schedules for a similar, or lower, cost than a single new house and land package

✓

You like the idea of keeping optionality: sell one villa later, keep the other, or hold both

Not a fit

A single villa may suit you better if

✕

You'd rather manage one tenancy than two, even at a similar entry cost

✕

You need to access the money you put in within the next 12 months

✕

You haven't had a first conversation about your own strategy yet, that's always where we start

✕

You'd rather skip strategy and just buy something off a list

Not sure?

That's exactly what the first call is for

We'll look at your numbers and tell you honestly whether a dual villa, a single villa, or something else entirely is the right next step for you.

No pressure either way. Just a clear answer.

Book My Free 15-Minute Call
If the numbers don't stretch to a dual villa yet

A single villa is still an affordable way in.

A dual villa is the strategy built to do the most work, but it isn't within everyone's budget from day one. If that's where you're at, a completed single villa is available from around $435,000, a genuinely affordable entry point into new property, at a price point that's hard to find elsewhere.

Because you're buying a completed home rather than land and build, you won't get the equity uplift a dual villa is designed to manufacture during construction, that's the trade-off for the lower entry cost and the simpler path in. What you still get is a brand-new, freestanding home on its own title, not a strata-titled, body-corporate-levied unit.

Finance works the same way it would for any established property purchase, it isn't a harder or more complex process, and where the numbers allow later on, you can always step up to a dual villa.

Talk through starting with one

From $435,000

A brand-new, freestanding villa on its own title. No strata fees, no special levies, no body corporate.

$1,000 holding deposit, then 20%

A $1,000 deposit secures it, then 20% of the purchase price, in cash or through equity release, takes you to settlement.

No manufactured uplift, still a foothold

You're buying at completed value, not land-and-build value, so there's no built-in equity uplift. What you get instead is an affordable, low-maintenance way onto the property ladder.

Backed by the same track record

Every dual villa gets the same scrutiny as every other strategy we build.

17+
Years in the Australian property market
1,346+
Client strategies built and executed
95%
Of developments rejected before they reach a client
4.6 ★
Google rating, 67 independent reviews
Common questions

Dual villas, explained plainly.

What exactly is a dual villa?
Two separate, self-contained new dwellings built on a single block of land. Each is a two-bedroom villa with its own entrance, kitchen and laundry, a bathroom with a separate toilet, and a single car space, and each is leased to its own tenant. The land is shared, the two homes are not.
Is a dual villa more expensive than a single investment property?
Usually not. A dual villa package is typically cheaper than, or on par with, building a single new house and land package of a similar size, while producing two rents and two depreciation schedules instead of one, because the land cost and stamp duty are shared across both villas rather than carried by one. We model the full numbers, land, build, combined rent and combined deductions, against a single-villa alternative in your strategy session (see an illustrative example), so you can compare the real picture rather than guess at it.
How much do I need to get started?
A $1,000 land holding deposit secures your position, then 20% of the purchase price, in cash or through equity release from an existing property, takes you through to settlement. Your independent broker will confirm exactly how that applies to your situation.
Do I end up with one title or two?
Two. We only build dual villas on land we can split, so both dwellings are designed to be separately titled on completion. That's a condition we screen for before a site is ever put in front of a client, not something we hope works out later.
Can I sell one villa and keep the other?
Yes. Because both villas are separately titled at completion, you can sell one, use the proceeds against your home loan, and keep the second producing income. Or sell both, or hold both. Rather than one property to sell (or not), you have two, and a real choice about what to do with each one.
Is finance harder to arrange for two dwellings on one block?
No. It works the same way as financing any single house and land package, one land purchase, one construction loan. Lenders factor in the combined rental income from both villas when assessing serviceability, which typically makes it easier, not harder, to get across the line. We bring in independent mortgage brokers early in your strategy session so your finance position is clear before anything is committed to, and finance is typically structured to cover repayments through the build, with rent taking over once each villa is tenanted.
What if one villa is vacant?
The other villa keeps producing rent. That's the core resilience benefit of the strategy: a single vacancy reduces your income, it doesn't remove it, the way it can with one investment property. Brand-new villas also tend to lease faster than established stock, and leasing typically starts several weeks before completion to minimise any gap.
Does every block allow a dual villa?
No, and that's exactly why we don't just take any site. Dual occupancy and title separation depend on zoning, lot size and council rules, so we only put land forward once we know both villas can be built and separately titled, and the underlying growth and rental fundamentals stack up. Most sites we assess don't make it to a client.
Can I start with just one villa instead of a pair?
Yes, see starting with one villa below. A completed single villa can be available from around $435,000 as a lower entry point, and something we can talk through in your strategy session.
Will I be out of pocket during the build?
Finance is generally structured to cover loan repayments through the build period, arranged with a broker from our network. Once each villa is tenanted, rent takes over.
What happens if the valuation comes in low?
The valuation that occasionally comes in under contract price is the bank's valuation done before construction starts, the one used to set up your loan. If it lands a little light, we work with your broker to adjust the finance structure, for example the loan-to-value split, to keep the deal on track. Once the villas are actually built, valuations typically come in at or above the completed value we modelled. That gap is the equity uplift the strategy is designed to manufacture, not a risk it's exposed to.
Why are the villas kept relatively simple?
On purpose. A well-built, simpler villa is what lets two homes fit comfortably on one block, and that's what creates the equity uplift and keeps both villas easy to rent and easy to sell. Every design choice is made to serve rent, resale and long-term return, not to impress.
Where do you build dual villas?
Right now, Tasmania first. It's the most affordable state market in the country, with a rental vacancy rate in the emergency range and a 2026 tax reform that keeps the concessions new builds rely on. See why we're building in Tasmania right now for the full picture, including St Helens as a live example.
Is the first call genuinely free and no-obligation?
Yes. It's 15 minutes, it's free, and there's no obligation. If a dual villa isn't the right tool for your situation, we'll say so and point you toward what is.
Take the first step

One purchase. Twice the outcome.
Let's see if it fits your numbers.

Book a free 15-minute intro call with a Property Investment Strategist. We'll model a dual villa against your situation and tell you honestly whether it's the right strategy for you.

Book My Free 15-Minute Call

Or call us on 1300 747 867  ·  admin@pistore.com.au